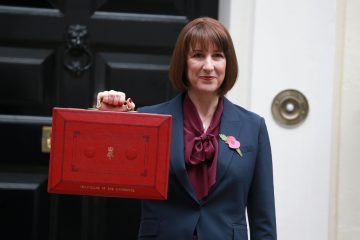
Chancellor John Healey delivered his first Budget on 28 October, unveiling a range of measures affecting household finances, businesses and the wider economy. The Autumn Budget 2026 goes through changes to taxation and plans for investment. But what will these announcements mean ? This article looks at the key changes, who they will affect and when they are due to take effect.
Expenses
From 6 April 2028, the government will remove the £2,500 threshold that requires taxpayers to file a Self Assessment return to claim tax relief on employment expenses. Taxpayers with claims above £2,500 will be able to claim through PAYE using form P87 or the PAYE Expenses service, with supporting evidence. As for the mileage expenses, the 45p figure was raised to 55p with effect from 6 April 2026, and the 25p figure will be raised to 35p from 6 April 2027.
Savings and Pensions
Last year it was announced that there would be a restriction on the amount that people under 65 could invest in a cash ISA, to take effect in April 2027. Chancellor Healey has cancelled this change, so it will still be permissible to invest £20,000 in a cash ISA or a stocks and shares ISA or a combination of the two.
The Chancellor has made no changes to the reliefs available for contributions to pension schemes or withdrawals from them. The maximum amount that can be withdrawn as a tax-free lump sum remains £268,275 unless the person is entitled to ‘protection’ in relation to the original introduction of the Lifetime Allowance or any of the subsequent reductions of the limit.
There has also been no change to the forthcoming restriction on ‘salary sacrifice’ arrangements. From April 2029, any amount within such an arrangement in excess of £2,000 will be subject to employer and employee NICs as if cash salary has been paid.
Payroll benefits
It had been intended that nearly all benefits would be subjected to mandatory payrolling from 6 April 2027, but last June it was announced that this would be restricted to only certain benefits: company cars, vans, fuel and medical benefits.Mandatory payrolling is due to apply to all other benefits from 6 April 2028 (except for beneficial loan and accommodation benefits).
From 2027/28, the employer Class 1A NICs on any payrolled benefits will have to be paid each pay period, rather than annually in arrears. It is important that all businesses affected by these changes are well prepared and that employees are made aware of the impact there will be on their payslips and net pay.
Dividend income
For 2027/28, the dividend allowance is unchanged at £500. As HMRC does not routinely receive information about dividends received by taxpayers, this low limit is likely to require people to file tax returns to declare even small tax liabilities on dividends.
In 2027/28, the basic, higher and additional rates on dividend income over £500 are unchanged at 10.75%, 35.75% and 39.35% respectively.The higher rate also applies to tax payable by close companies (broadly, those under the control of five or fewer shareholders) on ‘loans to participators’ that are not repaid to the company within 9 months of the end of the accounting period.
Capital Gains Tax
For 2027/28, this remains frozen at £3,000 for individuals and deceased’s estates, while for most trusts the figure remains £1,500. There are no changes to the main rates of CGT. The tax rate for qualifying gains remains 18%, but the lifetime limit for such gains is cut from £1 million to £500,000 for disposals from 6 April 2027.
For a higher or top rate income taxpayer with £1 million of qualifying gains, this will increase their CGT payable by £30,000. The Chancellor announced that a new relief ‘will support founders and early investors who have made a significant long-term contribution to the creation and development of the UK’s most high-growth and innovative companies.
Business Tax
From 1 January 2027, the permanent main-rate First Year Allowance (FYA) for qualifying new plant and machinery will increase from 40% to 50%. The main-rate FYA is available to companies and unincorporated businesses and, unlike full expensing, can apply to qualifying assets acquired for leasing.
From 1 April 2027 for companies and 6 April 2027 for unincorporated businesses, the main-rate writing-down allowance (WDA) will reduce from 14% to 12%.
From 1 April 2027, additional support will be available for qualifying retail, hospitality and leisure (RHL) properties in England. The rateable value threshold for 100% Small Business Rate Relief (SBRR) will increase from £12,000 to £18,000.Business rates relief for pubs, social clubs and most live music venues will increase from 15% to 35%.
Please contact us if you wish to have a copy of the summary of the Budget so we can help you and your business.